

Choosing the right savings account – Let’s break it down
Once again, I’ve been invited to channel my thoughts and perspectives – previously shared with my colleagues into a format that our members might genuinely enjoy. Choosing the right savings account to meet your goals can be a minefield, further exacerbated by nearly all the data available in the world at your fingertips, where information (and I speak from bitter experience) can be somewhat overwhelming. So, what I have tried to do is explain the most common types of savings accounts and how they can fit different goals and needs.
Easy access savings accounts
These can also be known as instant access saving accounts; this type of savings account gives you pretty much immediate access to your money. You pay cash into them, earn some interest on your savings, and take out your money whenever you want, with no fees or charges. Keep in mind that some institutions will limit the number of withdrawals you can make.
You can typically open an easy access savings account online in a few minutes; however, easy access accounts tend to offer lower interest rates than other savings products and that these interest rates are variable, they can go up and down depending on changes in the market.
An easy access savings account might be a good choice if you:
• Need instant access to your money, for example, if this is your emergency fund.• Need to start small with your savings.
• Want to add money to your account whenever you like.
Notice savings accounts
Instead of allowing instant access to your funds, a notice savings account requires you to give advance notice before taking your money out. This means that you need to submit a request for withdrawal. Depending on your bank or building society, you can do this online, or you may need to mail a signed request form. With some providers you won’t be able to withdraw before your notice period is complete. Others may let you withdraw early, but only if you pay an interest charge. The withdrawal notice period varies depending on the institution and can range from anywhere between 7 days to 195 days.
Notice accounts generally require a higher minimum opening deposit when compared to easy access accounts, however they tend to offer a higher interest rate. You can also expect that the longer the notice period, the higher the interest rate.
Generally, notice account rates tend to be variable, however an added benefit is that notice is reciprocal, i.e. the institution will give you notice before implementing a rate reduction.
A notice savings account might be a good choice if you:
• Want to save up for a goal with a specific time frame, such as paying for a house deposit or a wedding.• Want to put a barrier between you and your money to avoid impulse spending.
• Don’t need instant access to your savings.
Fixed term savings accounts
Also known as fixed rate bonds or fixed rate accounts, these accounts let you lock your money away for a set period, usually one to five years. You won’t be able to access your money before the end of the agreed term, or if you’re able to, you’ll likely incur an interest charge.
In return, for the length of the term, you’ll get a guaranteed interest rate that is generally higher than what you’d get from other savings accounts. This means you’ll be protected if interest rates fall in the future. But you may miss out on potential earnings if interest rates go up. Typically, you’ll need at least £1,000 for a minimum deposit.A fixed term savings account might be a good choice if you:
• Have a lump sum that you’re willing to lock away for long-term goals.• Want a fixed interest rate for the term duration and a guaranteed return on your savings.
• Don’t want to add money to your savings regularly.
Regular savings account
Regular savings accounts require you to put away a certain amount of money each month for an agreed period, typically 12 months. Depending on your bank, the monthly commitment can be anywhere between £10 and £500. You could face an interest charge if you miss a deposit or take money out during the agreed term.While regular savings accounts come with strict terms and conditions, they often offer higher interest rates than easy access or notice accounts. They can also help you develop a saving habit and be disciplined with your money, especially if you struggle to save towards a specific goal.
A regular savings account might be a good choice if you:
• Have a reliable source of income for the monthly deposit.• Want a higher interest rate.
• Want to save a specified amount each month.
• Don’t need emergency access to your funds.
Savings and tax treatment
While you may need to pay tax on interest earned on your savings in the UK, there are several tax-free allowances you could take advantage of.
Personal allowance
This is the set amount of income you can earn tax-free each financial year. For the 2025/2026 tax year, the personal allowance is £12,570. You can use your personal allowance to shelter interest on your savings from tax if you haven’t used it up on your wages, pension, or other income. Your allowance depends on the income tax band you fall into: • If you’re a basic rate (20%) taxpayer, your allowance is £1,000.• If you’re a higher rate (40%) taxpayer, your allowance is £500.
• If you’re an additional rate (45%) taxpayer, you won’t have a personal savings allowance.
Alternatively, you can use individual savings accounts (ISAs) to protect your savings from tax.
Individual savings accounts
With ISAs, you don’t have to pay tax on the interest you earn. However, there is a limit on how much you can deposit into an ISA each tax year, known as your ISA allowance, which is currently £20,000. Note that if you don’t use all of your allowance before the end of the tax year, you can’t carry over any unused allowance to the next year. Your ISA allowance resets on April 6th each year.An ISA might be a good choice if you:
• Want to earn tax-free interest on your savings.• Want to save for long-term goals, such as retirement or your first home.
• Want to deposit your money however you like, in a one-off lump sum or monthly payments, as long as you don’t go over the yearly ISA allowance.
Final thoughts…
If you’re thinking about opening a new savings account, consider your goals, how much you have to get started, and how often you need to access your funds. Once you’ve picked the account that best suits your situation, look around for offers from different institutions. While a higher interest rate is attractive, you should also pay attention to the quality of customer service.
Since each savings account has its own terms and conditions, make sure to read and understand them before you apply. Watch out for hidden fees and charges. Last but not least, review your savings account once or twice a year to see whether it’s still the right place to grow your money. If you decide to switch accounts, remember to check for any additional charges.
Jon Sweeting – Product Manager (Savings)
Related Articles

Industry
JUL 31, 2026
Fixed Rate product update
FOR INTERMEDIARY/PROFESSIONAL ADVISORS ONLY. NOT FOR CONSUMER USE.
Latest News
JUL 10, 2026
Harpenden wins ‘Best Local Building Society’ at the 2026 What Mortgage Awards
Harpenden Building Society wins ‘Best Local Building Society’ for the 12th year in a row, as well as being marked ‘Highly Commended’ in the ‘Best Specialist Lender’ and ‘Best Large Loan Lender’ categories.
Industry
JUN 09, 2026
Harpenden launch Expat mortgages
FOR INTERMEDIARY/PROFESSIONAL ADVISORS ONLY. NOT FOR CONSUMER USE.
Community
MAY 20, 2026
Jon’s Savings Blog – ISA Changes in 2027
There’s a famous saying: “The best time to plant a tree was 20 years ago. The second‑best time is now.” Well, when it comes to ISAs… the tree is about to get a little smaller.
Industry
APR 22, 2026
Member Notice – Staff training 23rd April
Latest News
APR 17, 2026
A Q&A with our CEO Tracie
Here’s a quick Q&A from our CEO Tracie Meadows diving into our new rebrand.
Industry
JAN 22, 2026
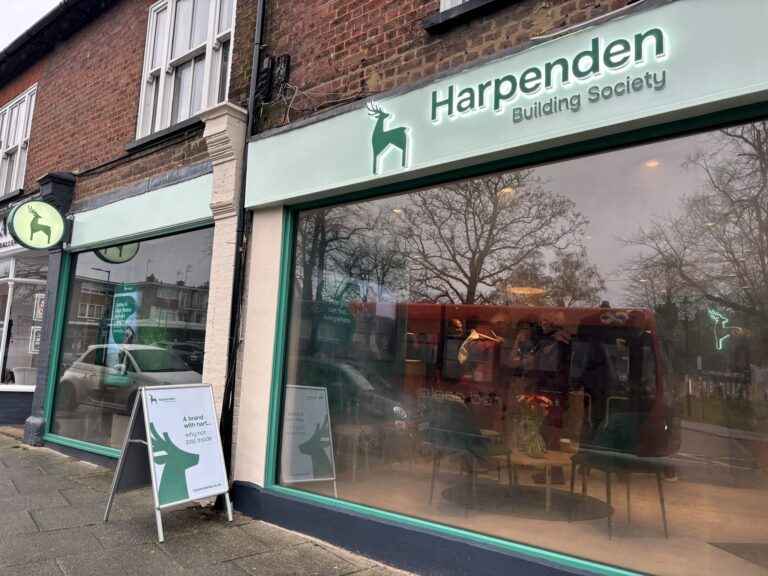
We celebrate our new branch opening in Harpenden
We are thrilled to announce the launch of our brand-new branch, located right on the High Street, in one of the busiest areas of Harpenden. The doors opened on the 15th of January, with the event being kicked off by celebrations and excitement from colleagues and members alike. Local members were offered the chance to visit and be a VIP guest to see the grand opening and were greeted by some food and hot drinks while they got to have a look around the new branch or ask our branch team any questions that they had. It was lovely to see so many members come and show their support for us. Also there to show their support were colleagues from the Harpenden Hopper, a local charity that we have supported for a few years. We were also joined by both the Mayor of Harpenden as well as our local MP. After some lovely speeches from our Chair and the Mayor all about the community-focus of the branch, the ribbon was cut, and our new Harpenden branch was declared officially open. You might notice a refreshed look to our brand both inside and outside the building. Our new branch aims to deliver confidence to our members. Being a mutual, our focus will always be about putting our members first. The branch is a nod to our heritage within Harpenden, as well as our renewed commitment to the community and our members. The customer experience is always at the front of our minds, and the new branch has been designed with this in mind. The colourful interior, while looking refreshed and playful, creates a welcoming atmosphere for our friendly branch team to help customers in the best way they can. This branch also comes with a technical upgrade, with iPads and digital screens to aid in the member's experience. With these new upgrades, we can assure our members that the clarity and trust they hold with the Society is still there and isn't going away any time soon. Our branch colleagues are as can-do and helpful as ever, but with a larger and more prominent location, we are setting our sights on an improved future. Tracie Meadows, the CEO of Harpenden Building Society said: "We at Harpenden Building Society always put our members first. Our new branch is just that. It's us giving back to our members and the community in Harpenden." She continued that, "We're giving our customers a better experience, while still being the friendly building society that's always ready to lend a hand. We want people to leave the branch feeling confident in us, and in their financial decisions." Our new Harpenden branch represents an exciting next step for the Society, and is just the beginning - there's definitely more to look forward to in the future.